


In accordance with the Law on Accounting, as well as the policies and strategies of the Party and the State regarding economic and financial development and international integration, the Ministry of Finance (MoF) has been tasked with providing guidance on the adoption of International Financial Reporting Standards (IFRS) in Vietnam. This serves as a vital foundation for enterprises to implement IFRS in a consistent manner, thereby enhancing the transparency of financial reporting and meeting the requirements of international integration.
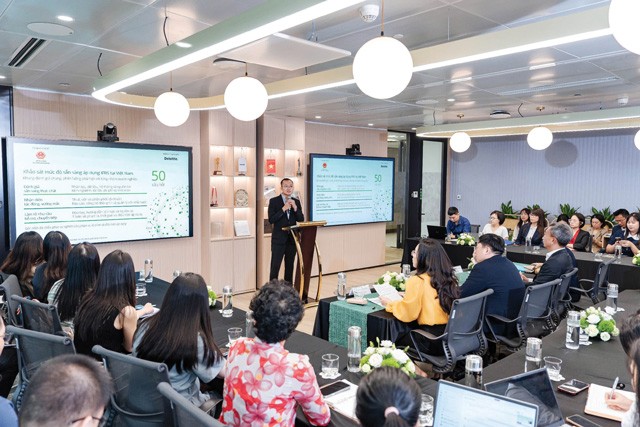
Speaking at the event to launch a survey on the adoption of the IFRS in Vietnam, held on November 5 by the Department of Accounting and Audit Management and Supervision under the MoF in collaboration with Deloitte Vietnam, Mr. Dang Quyet Tien, Director of the Department of Accounting and Audit Management and Supervision, said that preparations have been thorough given the practical requirements, the need to accelerate integration to enhance the standing of Vietnam’s capital markets, and the fact that the stock market has already been upgraded. “Consequently, we must expedite our actions and introduce concrete products,” he continued. “The objective is to ensure the rapid and early adoption of the IFRS framework.”
Mandatory requirement
Based on Deloitte’s experience, Ms. Tran Thi Thuy Ngoc, Partner, Growth Leader at Deloitte Vietnam, said the adoption of IFRS is far more than a simple transition from one national accounting standard framework to another. It is a comprehensive transformation that touches upon various facets of an open market economy, reflected through the lens of a company’s financial health, its obligations to the State, employees, and consumers, its approach to risk management and mitigation, its governance of information and data, its relationships with investors and the public, and the formulation and execution of its business strategy.
Consequently, IFRS should be viewed not merely in terms of compliance cost but rather of the long-term value it can deliver: enhancing the transparency and comparability of financial information; improving data quality and governance discipline; facilitating access to international investors, capital, and markets; strengthening communication with shareholders, banks, customers, suppliers, and other stakeholders; and bolstering risk management while standardizing reporting processes across both individual entities and entire corporate groups.
According to Deloitte Vietnam, while IFRS was previously viewed primarily as a new set of requirements for accounting, financial reporting, and statement presentation, it is now increasingly approached by businesses as a strategic tool. Many enterprises have proactively studied the standards, invested in staff training, conducted gap analyses, developed models, piloted the preparation and presentation of financial statements, and established phased implementation roadmaps. “These are highly-positive indicators, reflecting both the genuine demands of the capital market and the proactive commitment of the business community toward integration and the enhancement of market transparency,” Ms. Ngoc added.
As a publicly-listed company, the Hoa Phat Group has seen foreign ownership reach as high as 35-39 per cent. When reviewing financial statements prepared under local standards, which differ from international standards, foreign investors frequently reached out to its communications department with numerous inquiries, particularly regarding merger and acquisition (M&A) activities. This created significant challenges in providing clear explanations.
Furthermore, when operating entities abroad such as in Singapore or Australia, the Group faced major obstacles in financial reporting. Specifically, after preparing IFRS-compliant financial statements for these foreign entities, they had to dedicate resources to convert them into Vietnamese Accounting Standards (VAS) before they could be consolidated into reports in Vietnam.
Ms. Pham Thi Kim Oanh, Head of Finance at the Group, said that although it is not yet a fully-fledged multinational corporation, its long-term vision for sustainable growth and international expansion makes the consolidation of financial statements under international standards essential, as this would eliminate redundant intermediate steps and the need to constantly switch between different accounting systems.
Similarly, an Eximbank representative noted that the bank’s practical experience has shown that financial statements prepared in accordance with IFRS provide exceptionally clear and transparent information; a fact highly-valued by both its senior management and its foreign partners.
Business challenges
Businesses currently face significant challenges and obstacles regarding the implementation of IFRS. Regarding human resources, Eximbank’s dedicated IFRS team currently consists of only about a dozen people. The bank must implement robust compensation and retention policies for this team to prevent them from being recruited by other organizations, as professionals with IFRS expertise are currently quite rare in the market. Meanwhile, the Hoa Phat Group employs over 500 accountants stationed around the country.
In terms of information technology, the Eximbank representative noted that IT systems tailored for IFRS are not yet widely available in Vietnam. Opting for established international solutions, however, entails significant costs.
In fact, when Hoa Phat engaged external services for an IFRS pilot project in one of its business segments, it became clear that complex calculations such as discounting or mark-to-market valuations cannot be handled manually using Excel. At the same time, implementing an Enterprise Resource Planning (ERP) system across the entire Group to manage these metrics, as well as fluctuations in inventory, accounts receivable, and accounts payable, is extremely costly. Current software solutions from technology providers meet only about 60 per cent of the Group’s requirements, leaving the remaining 40 per cent of the workload to be processed manually. “Therefore, we have a critical need for specialized technological tools and software to support our IFRS implementation,” Ms. Oanh said.
Regarding asset valuation, companies face challenges in identifying suitable partners and appropriate valuation methodologies. The assets of large conglomerates, she explained, particularly real estate and inventory, are distributed around the country. To assess these assets at fair market value, companies require valuation partners with high professional competence who can ensure independence and objectivity.
With tax policy, a gap already exists between VAS and current tax regulations, which is expected to widen even further with the adoption of IFRS. “Tax expenses are a major concern for businesses, so we hope that reasonable costs incurred under IFRS will be recognized as tax-deductible,” she added.

These are highly-positive indicators, reflecting both the genuine demands of the capital market and the proactive commitment of the business community toward integration and the enhancement of market transparency.
As for the timeline for disclosure and adoption, Hoa Phat is interested in being among the first entities to voluntarily adopt IFRS. However, due to the aforementioned challenges, the Group has limited its involvement to observation, internal practice, and independent research, rather than full-scale implementation. It urges State authorities to announce a clear roadmap soon, allowing businesses to proactively prepare for the transition. For instance, if listed companies are required to adopt IFRS for the 2030 reporting period, they would need to prepare opening-balance data covering the years 2027-2029.
From the perspective of State regulatory authorities, Mr. Tien said the MoF has tasked the Department of Accounting and Audit Management and Supervision with announcing the widespread adoption of IFRS for eligible enterprises in Vietnam no later than June 2027.
In this context, Mr. Tien offered several specific recommendations. For State authorities, including the Department of Accounting and Audit Management and Supervision, the State Securities Commission, the General Department of Taxation, and individual tax officials, there is a need to innovate and enhance their capacity for engagement. The MoF intends to facilitate the participation of other entities, such as the State Bank of Vietnam and the State Audit Office, in training sessions to help them better understand IFRS.
As for the business community, leaders and accounting and finance professionals are encouraged to view this as both an opportunity and a responsibility. They are urged to complete the survey thoroughly and accurately, and to share their views candidly, ensuring that the resulting regulatory framework and roadmap are appropriate and well-aligned with the needs of enterprises. For consulting firms and service providers, this represents both an opportunity and a responsibility to partner with State authorities and businesses, assisting the broader community in the successful implementation of the IFRS program.
 Google translate